
Business Owners Policy Quotes: Quick Comparisons
A Business Owners Policy bundles property and liability coverage into one package, making it the smart choice for most small businesses. Comparing business owners policy quotes from different carriers helps you find the right protection at the right price.
At Beach Break Insurance Agency, we’ve helped countless business owners cut through the confusion and land policies that actually fit their needs. The right quote comparison takes just a few steps, and we’ll walk you through them.
What a Business Owners Policy Actually Covers
A Business Owners Policy combines commercial property insurance and general liability into one package, protecting both your physical assets and your financial exposure. Property coverage pays for damage to your building, equipment, inventory, and tools from fire, theft, vandalism, and weather events. Liability coverage handles claims when someone gets hurt on your property or your business causes property damage to someone else. You also receive business interruption coverage, which replaces lost income and covers operating expenses if a covered event forces you to shut down temporarily. Hartford customers report paying around $141 per month on average for a BOP, though your actual cost depends on your industry, location, and the specific risks you face. The real advantage here is simplicity: you get comprehensive protection without managing multiple policies from different insurers. Most small businesses need both property and liability coverage anyway, so bundling them into one policy makes financial sense and reduces administrative headaches.
Why a Single Policy Beats Buying Separately
Purchasing property and liability insurance as separate policies costs significantly more than combining them into a BOP. When you bundle, carriers typically offer discounts up to 10 percent when you add workers compensation to your BOP. That’s real money back in your pocket.

A single policy means one renewal date, one agent relationship, and one portal to manage certificates of insurance. You avoid coverage gaps that occur when separate policies don’t align properly. A BOP also simplifies claims handling because everything flows through one insurer rather than coordinating between multiple carriers when something goes wrong.
The Specific Risks Your Business Actually Faces
Your industry determines which BOP components matter most. A retail store faces different risks than a consulting firm, yet both benefit from property coverage for their equipment and liability for customer injuries. If you operate from rented space, your BOP covers your belongings and liability but not the building itself (which your landlord’s insurance handles). Construction businesses need higher liability limits because bodily injury claims run expensive. Food service operations face property damage from equipment breakdown and liability from foodborne illness claims. The Hartford BOP allows liability limits up to four million dollars in aggregate coverage, giving you flexibility to match your actual exposure. The right coverage level matters more than finding the cheapest quote, because underinsurance leaves you exposed to catastrophic losses that a policy discount won’t cover.
How Coverage Limits Shape Your Protection
Liability limits determine how much your insurer pays when someone sues your business. A four million dollar aggregate limit (the maximum The Hartford offers) protects you far better than a one million dollar limit if a serious accident occurs. Property coverage limits should reflect the actual replacement cost of your building, equipment, and inventory. If you own ten thousand dollars in tools but insure them for five thousand dollars, you absorb the loss yourself. Deductibles work the opposite way: higher deductibles lower your premium but increase what you pay out of pocket when you file a claim. Most small businesses choose deductibles between five hundred and two thousand five hundred dollars, balancing affordability with reasonable out-of-pocket costs.
What Comes Next in Your Quote Comparison
Now that you understand what a BOP covers and why it matters, the next step involves comparing actual quotes from multiple carriers to see how coverage and price differ across insurers.
How to Compare BOP Quotes Without Wasting Time
Getting multiple quotes is the only way to spot real price differences and coverage gaps that matter. Most small business owners accept the first quote they receive, which costs them hundreds or thousands annually. You need quotes from at least three different carriers to see meaningful variation in pricing and coverage options. The Hartford, ERGO NEXT, CNA, Nationwide, and BiBERK all serve small businesses with different pricing structures and liability limits.
Request Quotes with Consistent Information
Request quotes online or call carriers directly with the same business information for each one-your industry, annual revenue, number of employees, property value, and location. This consistency lets you compare apples to apples rather than receiving wildly different quotes because you described your business differently to each insurer. Many carriers offer online quote tools that take fifteen to twenty minutes to complete. Write down the exact coverage limits, deductibles, and premium for each quote before moving forward. Spreadsheets work perfectly for this, with columns for carrier name, general liability limit, property coverage limit, business interruption limit, annual premium, and any available discounts. You’ll immediately see which carriers price aggressively in your industry and which ones offer superior coverage for a reasonable cost.
Evaluate Liability Limits and Deductibles
The Hartford offers liability limits up to four million dollars in aggregate coverage, which exceeds what many competitors provide. ERGO NEXT matches that four million dollar limit with a faster online claims process. CNA includes inflation protection automatically, meaning your coverage limits increase each year without you requesting changes-a feature most competitors charge extra for or don’t offer at all.
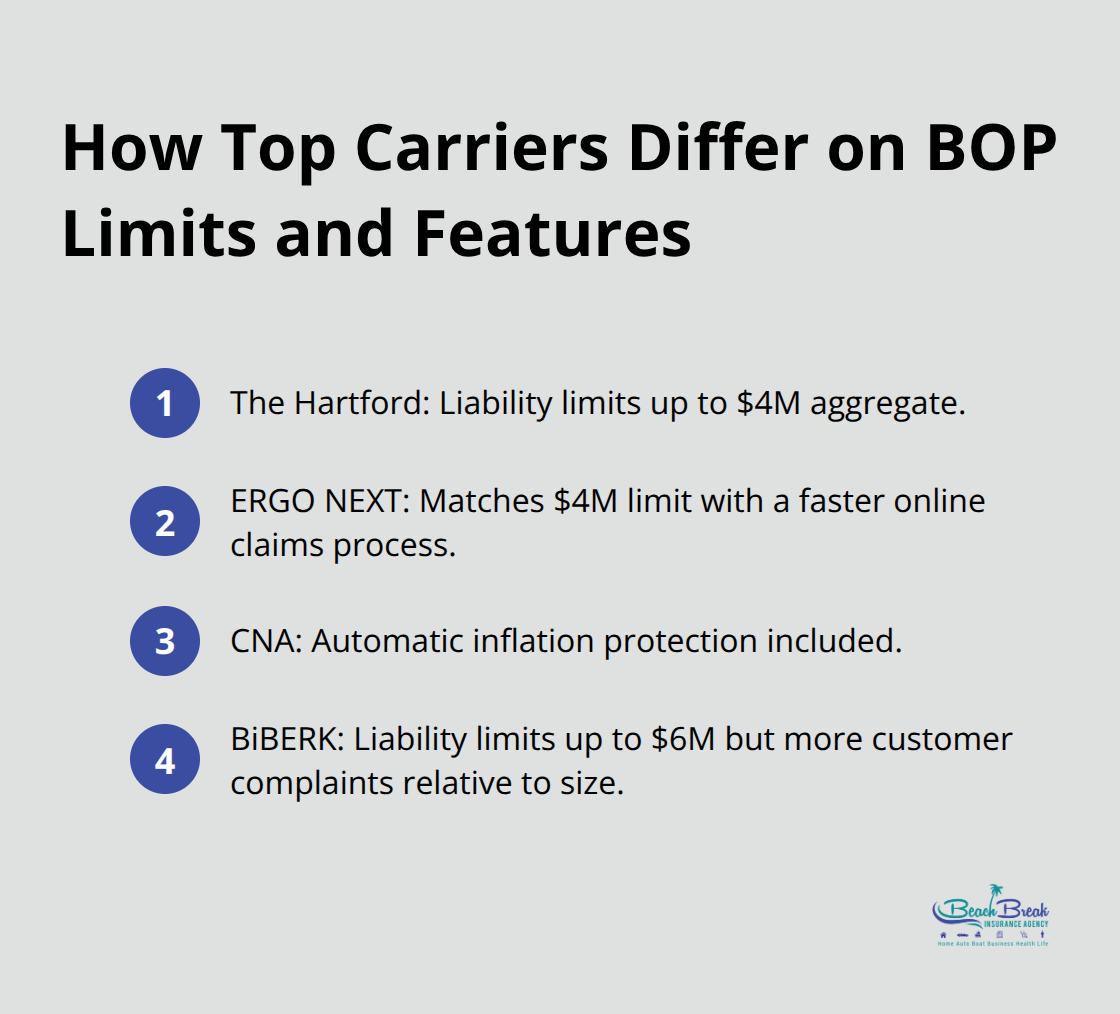
BiBERK pushes liability limits to six million dollars, the highest available, though they carry more customer complaints than expected relative to their size.
Deductibles typically range from five hundred to twenty-five hundred dollars, and jumping from five hundred to one thousand dollars usually saves ten to fifteen percent on your annual premium. Don’t chase the lowest deductible unless you file claims frequently; most small businesses go years without property claims, making high deductibles sensible. The difference between a four million and six million dollar liability limit might cost only fifty to one hundred dollars annually, making it worth the upgrade if your business faces serious injury exposure.
Compare Additional Coverages and Features
Review what additional coverages each quote includes at no extra cost versus what costs extra. Workers compensation, professional liability, cyber insurance, and commercial auto insurance rarely come standard in a Business Owners Policy but can be added through most carriers. Request certificates of insurance from each carrier to confirm they generate them digitally and instantly through their portal-this matters when clients need proof of coverage quickly.
An independent agency compares quotes from multiple top-rated carriers simultaneously, eliminating the need for you to contact each one separately and track down different requirements for each application. This approach saves you time while ensuring you evaluate all viable options side by side.
Once you’ve narrowed your choices based on price and coverage, the next step involves assessing your specific business needs to confirm the quote you select actually protects what matters most to your operation.
Tailoring Your BOP to Match What Your Business Actually Needs
Your industry, revenue, location, and operational risks determine which BOP features matter most and what you should actually pay. A photography studio in San Diego faces completely different exposures than a plumbing contractor, yet both need property and liability coverage. Start by identifying your highest-risk scenarios: What would cost you the most if it happened tomorrow? For a retail store, that might be a fire destroying inventory and forcing a temporary closure. For a consulting firm, it’s a client injury or a lawsuit over professional mistakes. Once you pinpoint these scenarios, you can evaluate whether standard BOP coverage handles them or if you need add-ons like professional liability or cyber insurance.
How Your Business Profile Shapes Your Premium
Your annual revenue matters because higher-revenue businesses typically need higher liability limits and more property coverage. A business generating fifty thousand dollars annually needs different protection than one generating five hundred thousand dollars. Location also shifts your costs significantly: businesses in high-fire zones pay more for property coverage, while urban areas with higher foot traffic increase liability exposure. Request quotes that reflect your actual situation rather than generic estimates, because carriers price based on your specific risk profile, not industry averages.
Factors You Can Control to Lower Your Costs
Several factors directly control your premium that you can influence. The Hartford’s data shows that small business customers pay an average of $1,687 a year for a Business Owner’s Policy, but this varies substantially based on your deductible choice, coverage limits, safety features in your building, and claims history.
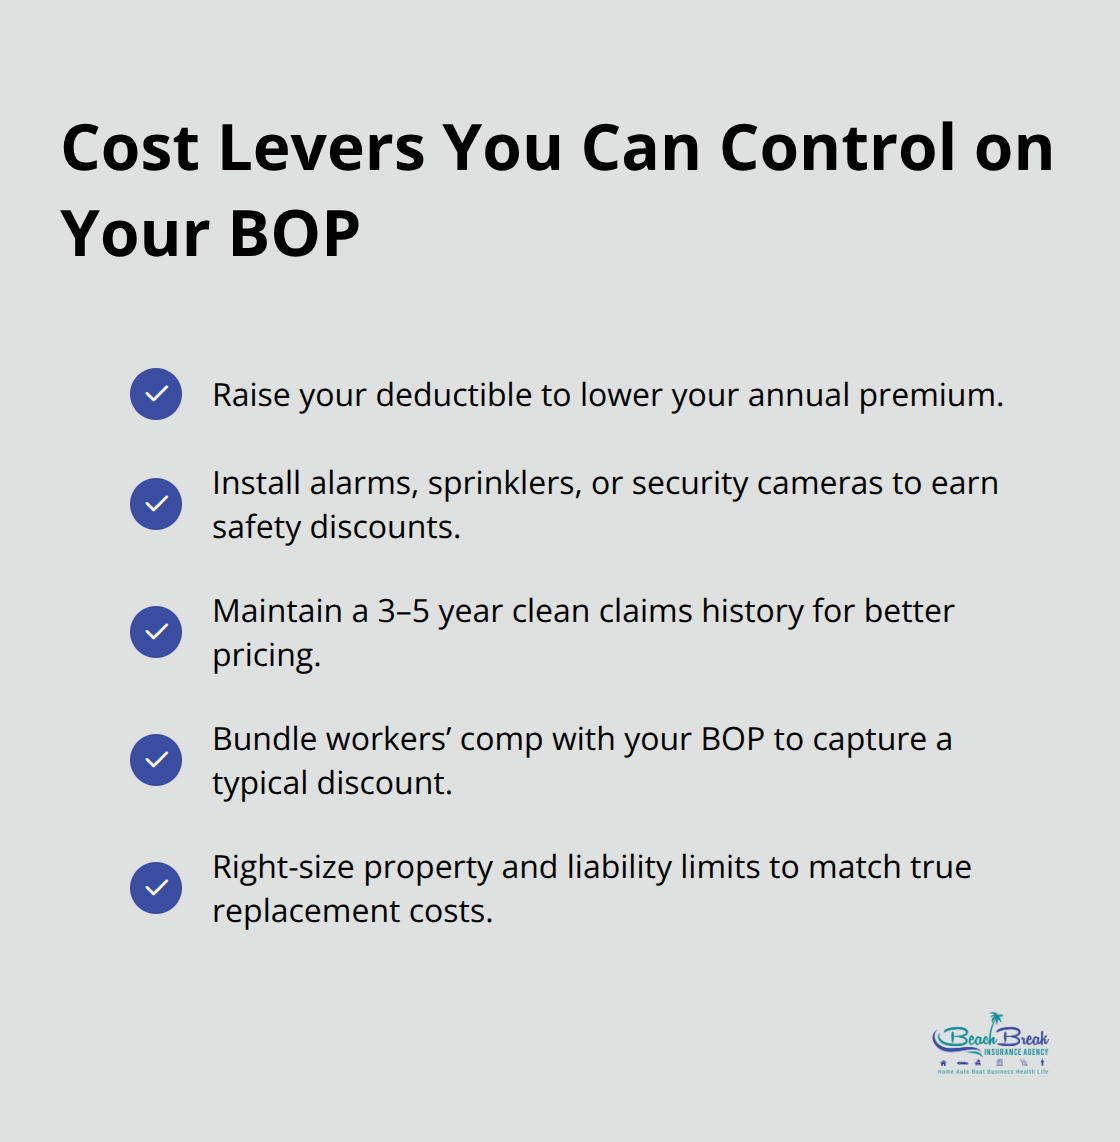
A five-hundred-dollar deductible costs more than a two-thousand-five-hundred-dollar deductible because the insurer assumes more risk. Installing alarm systems, sprinkler systems, or security cameras often qualifies you for discounts ranging from five to fifteen percent because these reduce your likelihood of loss. If you’ve gone three to five years without claims, mention this when requesting quotes because most carriers reward clean claims history with better pricing. Your number of employees significantly impacts workers’ compensation costs if you add it to your BOP, so bundling workers’ comp with your BOP often yields that ten percent discount.
Working with an Agent to Get the Right Coverage
An independent agency compares these variables across multiple carriers simultaneously, which saves you from requesting quotes individually and allows you to see exactly how each carrier weights different risk factors. This approach reveals which insurers price aggressively for your specific profile rather than generic small businesses. When you work with an agent rather than using online quote tools alone, you gain someone who understands your industry’s particular exposures and can recommend coverage limits and add-ons that actually protect your operation. The agent also handles endorsements as your business grows or changes, keeping your coverage aligned with reality instead of whatever you guessed was adequate when you first purchased the policy.
Final Thoughts
Comparing business owners policy quotes from multiple carriers reveals real price differences and coverage variations that matter for your specific operation. Most small business owners accept the first quote they receive, which costs them hundreds or thousands annually in unnecessary expenses or inadequate protection. You spot meaningful savings and superior coverage options only when you evaluate quotes from at least three different carriers side by side.
Request quotes with consistent information about your business, evaluate liability limits and deductibles across carriers, and review what additional coverages each option includes. Pay attention to features like digital certificates of insurance, inflation protection, and claims handling speed because these affect your experience when you actually need the policy. Your industry, location, revenue, and claims history all shape your premium, and understanding these factors helps you make informed decisions rather than guessing at adequate coverage levels.
At Beach Break Insurance Agency, we compare quotes from multiple top-rated carriers to deliver tailored coverage that fits your business needs and budget. Contact us to get started with your business owners policy quotes comparison and discover how much you could save while gaining better coverage.
The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation.
Artificial intelligence may have been used to generate text and images in some blog articles.


