
San Diego BOP Coverage: Streamlined Protection for Local Businesses
Running a small business in San Diego means protecting what you’ve built. A Business Owners Policy, or BOP, combines property, liability, and business interruption coverage into one streamlined package designed for companies like yours.
At Beach Break Insurance Agency, we’ve seen how the right San Diego BOP coverage can be the difference between a business that recovers quickly and one that struggles after an unexpected loss. This guide walks you through what you need to know to get protected.
What Your BOP Actually Covers
A Business Owners Policy combines three essential protections that work together to shield your San Diego operation. Property coverage protects your building, equipment, inventory, and furniture from damage caused by fire, theft, weather, and other covered perils. Liability coverage handles third-party claims when someone gets injured on your property or your business causes damage to their belongings-California commercial leases often require proof of liability protection before you can occupy the space. Business interruption coverage reimburses you for the income your business loses during a covered shutdown, including continuing fixed expenses like rent, payroll, and utilities, allowing your business to survive the financial hit while you rebuild.
Most San Diego businesses underestimate how quickly these losses add up. A single fire that closes a restaurant for two weeks costs $15,000 to $30,000 in lost revenue alone, not counting temporary repair expenses. The national median monthly cost for a new BOP runs around $80 according to Progressive Commercial data, though San Diego businesses typically pay between $50 and $150 monthly depending on property value, business type, and claims history.
Why San Diego Businesses Face Different Risks Than Other Markets
Your location creates specific exposures that inland businesses never encounter. Earthquake risk sits at the top of the list because standard BOPs explicitly exclude earthquake damage-a significant seismic event could leave you with no coverage unless you purchase an earthquake endorsement. Coastal properties face salt spray damage that corrodes metal fixtures and equipment faster than elsewhere in California. Businesses near wildfire zones must contend with smoke damage, evacuation orders, and ash accumulation that can halt operations for weeks.
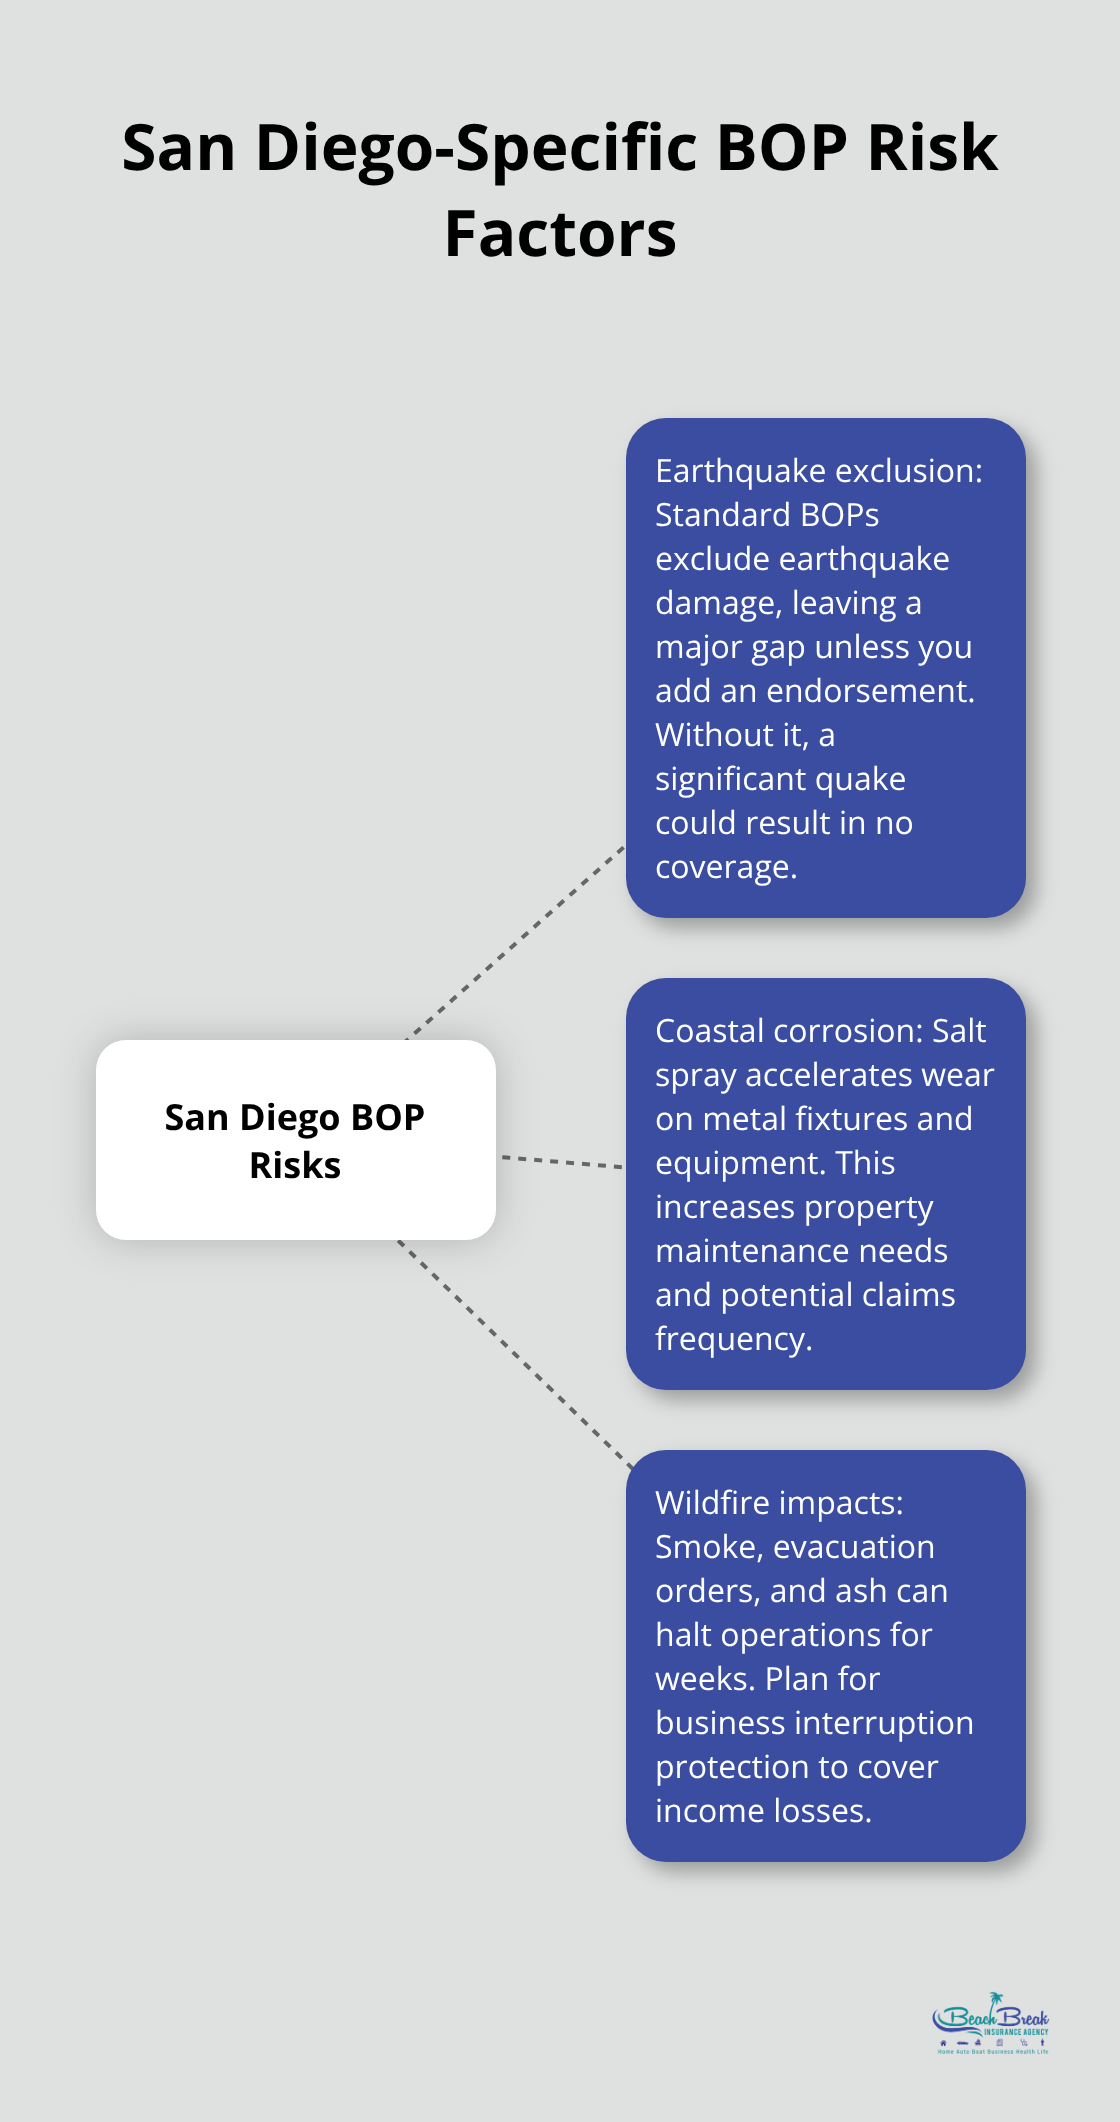
Property values in San Diego also tend to run higher than the national average, which means your inventory, equipment, and building improvements need adequate coverage limits to truly protect your investment. Many small business owners initially undervalue their property by 20 to 30 percent because they forget to include leasehold improvements, signage, tools stored off-site, and customer property in their possession. Accurate coverage limits from the start prevent a painful gap claim later.
How BOP Handles the Claims You Actually Face
Slip-and-fall injuries represent the most common liability coverage claim for retail and service businesses in San Diego, with settlements ranging from $5,000 to $25,000 depending on injury severity and negligence factors. Your BOP liability coverage handles the medical bills, legal defense costs, and settlement amounts when a customer legitimately gets hurt on your property.
Spoiled inventory claims hit restaurants, grocers, and food service businesses harder than most other industries, especially when equipment breakdowns or power outages destroy perishable stock. An equipment breakdown endorsement attached to your BOP costs roughly 10 to 15 percent more but protects against these scenarios that standard property coverage sometimes excludes.
Data breach claims have exploded across San Diego’s tech and professional services sectors, with notification costs alone running $5,000 to $15,000 per incident according to California data breach notification requirements. A cyber liability endorsement attached to your BOP fills this gap and covers breach notification, credit monitoring services, and public relations expenses when customer information gets compromised.
Assessing What Your Business Actually Needs
The right BOP starts with an honest evaluation of your assets and exposures. Your property value determines your coverage limits-underinsuring leaves you exposed, while overinsuring wastes premium dollars. Your industry shapes your liability risk profile; a consulting firm faces different exposures than a retail shop or restaurant. Your current policy may already cover some protections, or it may leave significant gaps that a BOP can address more efficiently than separate policies.
An independent agent can walk you through these factors and help you identify which endorsements make sense for your specific operation, ensuring your coverage actually matches your business rather than forcing you into a one-size-fits-all package.
How to Assess Your Business’s BOP Needs
Calculate Your Actual Property Value
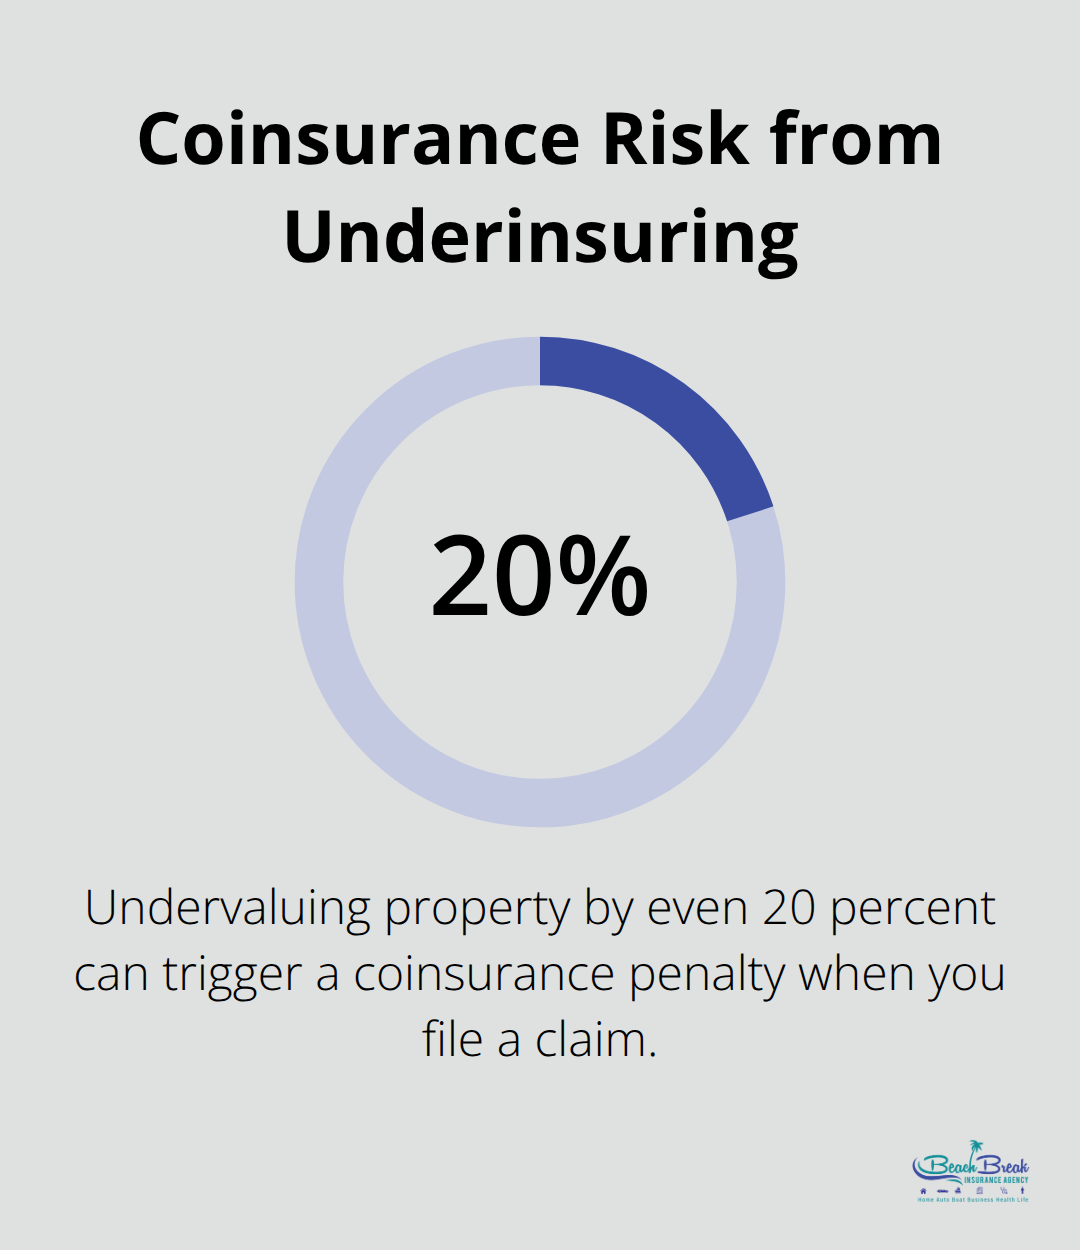
Most San Diego business owners undercount what they own. You need to list everything your business would have to replace: the building itself if you own it, all equipment and machinery, inventory, furniture, signage, tools, and any leasehold improvements you’ve made to a rented space. Custom-built reception desks, upgraded flooring, or specialized shelving represent real dollars that need coverage, yet many owners overlook these items entirely. Walk through your space with a notebook and photograph everything, then obtain replacement cost quotes for major items. If you own the building, contact your property tax assessor’s office for the assessed value, though this typically runs lower than actual replacement cost in San Diego’s current market. For rented spaces, pull your lease document-it usually specifies what improvements you’ve made-and add those costs to your equipment list. Undervaluing property by even 20 percent triggers a coinsurance penalty when you file a claim, since most carriers reduce payouts proportionally when you haven’t insured to value. Businesses that properly value their assets experience claim payouts covering full losses, while underinsured businesses face out-of-pocket costs averaging 15 to 30 percent of the claim amount.
Identify Your Liability Exposure by Industry
Your liability exposure depends entirely on what your business does and who enters your space. A retail shop faces slip-and-fall risks and product liability claims, while a consulting firm’s main exposure comes from professional errors that damage a client’s business. A restaurant combines slip-and-fall risk with food poisoning exposure and liquor liability if you serve alcohol. Ask yourself what could realistically go wrong and what it would cost if someone sued. California requires minimum auto liability limits of $30,000 per person and $60,000 per accident for commercial vehicles, but San Diego businesses operating in higher-income areas often face settlements that exceed these minimums significantly.
Spot Coverage Gaps in Your Current Policy
Coverage gaps appear when your current policy excludes something your industry regularly encounters. If you operate near the coast, corrosion damage from salt spray isn’t typically covered under standard property policies without an endorsement. If you handle customer data, a standard BOP lacks cyber liability coverage entirely, yet California data breach notification laws require you to notify affected residents at your own expense. If equipment breakdowns would halt your operations, standard property coverage sometimes excludes this scenario unless you add business interruption with equipment breakdown protection. Pull your current policy declarations page and list exactly what coverages you have, then compare that against the specific risks your operation faces. An independent agent can help you spot these gaps quickly rather than discovering them during a claim.
Compare Your Current Coverage Against Real Risks
The honest assessment requires matching what you own and what could go wrong against what your policy actually covers. Coastal properties face salt spray damage that corrodes metal fixtures and equipment faster than elsewhere in California. Businesses near wildfire zones must contend with smoke damage, evacuation orders, and ash accumulation that can halt operations for weeks. Standard BOPs explicitly exclude earthquake damage-a significant seismic event could leave you with no coverage unless you purchase an earthquake endorsement. Property values in San Diego tend to run higher than the national average, which means your inventory, equipment, and building improvements need adequate coverage limits to truly protect your investment.
Take Action on Your Coverage Assessment
Once you’ve identified your property value, liability exposure, and coverage gaps, you’re ready to explore BOP options that actually match your business. An independent agent can walk you through these factors and help you identify which endorsements make sense for your specific operation, ensuring your coverage matches your business rather than forcing you into a one-size-fits-all package. At Beach Break Insurance Agency, we quickly compare quotes from multiple top-rated carriers to deliver tailored coverage that aligns with your actual needs and budget.
Finding the Right BOP Without Overpaying
Compare Quotes Across Multiple Carriers
Bundling policies with a single carrier typically saves San Diego small businesses between 10 and 25 percent on their total premium costs, according to Progressive Commercial data. If you already carry commercial auto or another business policy, adding a BOP to that same carrier often triggers automatic discounts that compound your savings. However, this bundling advantage only works if the carrier’s BOP pricing remains competitive for your specific industry and property profile.
Many San Diego business owners assume their current insurance provider offers the best BOP rates, then skip the comparison step entirely and leave hundreds of dollars annually on the table. The smarter approach involves requesting quotes from at least three different carriers before making a decision, since BOP pricing varies dramatically based on how each insurer assesses your particular risk. A restaurant owner might find Hartford’s rates significantly lower than Progressive’s, while a consulting firm sees the opposite pricing pattern.
Progressive Commercial underwrites over 300 business types and quotes online instantly, making initial comparison shopping fast and painless. Independent agents in San Diego represent multiple carriers including Nationwide, Hartford, Next, and Progressive, which means they can pull quotes from several companies simultaneously rather than forcing you to contact each carrier separately. This independent agent advantage saves you hours of phone calls and ensures you’re comparing apples to apples across similar coverage limits and deductibles.
Customize Coverage Limits to Match Your Operation
Customizing your BOP requires matching coverage limits and endorsements to your actual business size and risk profile rather than accepting whatever package the carrier suggests. A 2,000-square-foot retail shop needs vastly different property limits than a 10,000-square-foot warehouse, yet both might receive the same standard BOP template if you don’t push back during the quoting process.
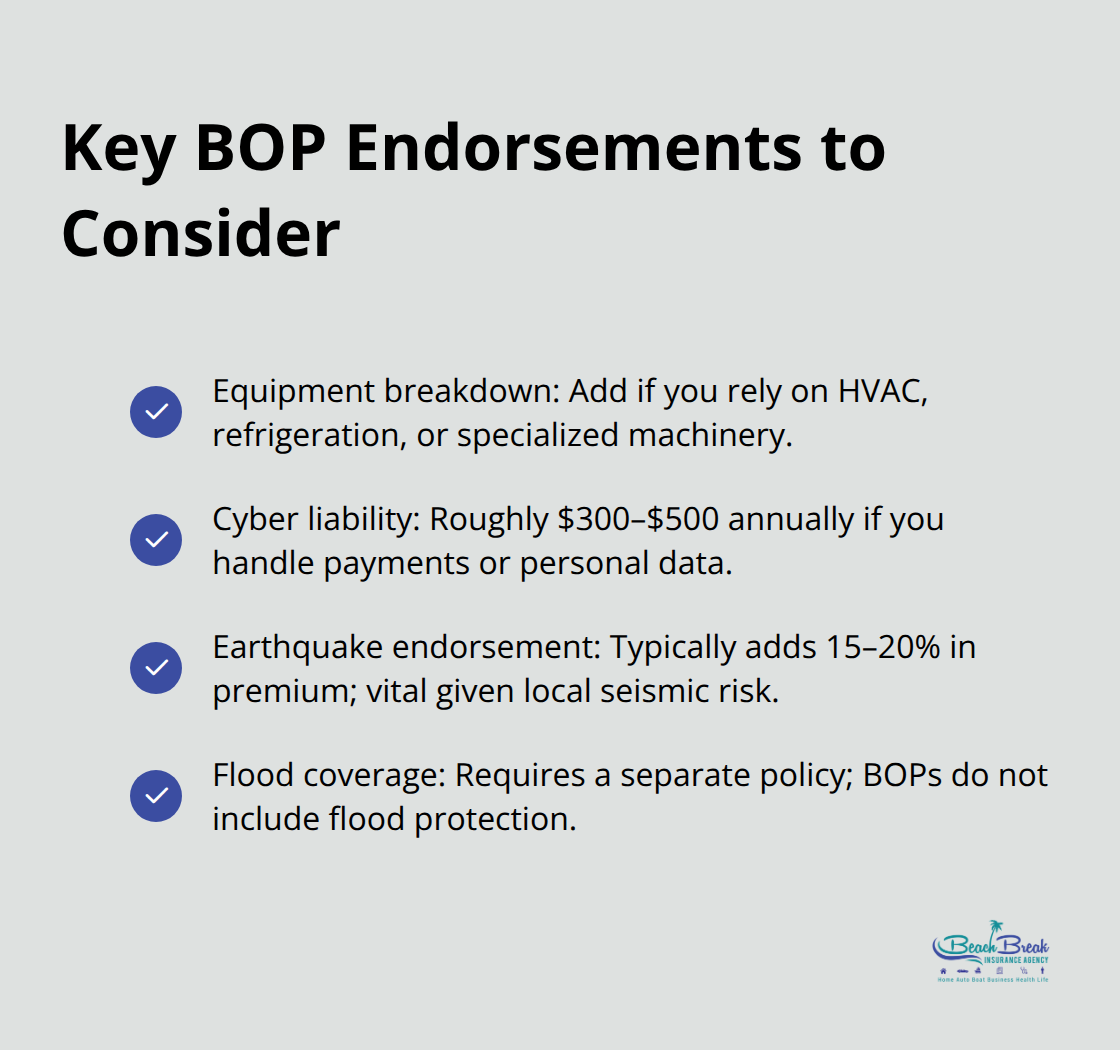
Equipment breakdown endorsements typically cost 10 to 15 percent more than standard coverage but become essential if your operation depends on HVAC systems, refrigeration, or specialized machinery. Cyber liability endorsements run roughly $300 to $500 annually and should be non-negotiable for any San Diego business handling customer payment information or personal data. Earthquake endorsements cost 15 to 20 percent additional premium but prove invaluable given San Diego’s seismic activity, while flood coverage requires a completely separate policy since no BOP includes this protection.
Adjust Your Deductible Strategy
Your deductible choice directly impacts your monthly premium, with higher deductibles like $2,500 or $5,000 reducing costs by 20 to 30 percent compared to standard $1,000 deductibles. This strategy only makes sense if you can actually afford the higher out-of-pocket cost when a claim occurs. Test different deductible levels and endorsement combinations to find the sweet spot where coverage remains comprehensive without wasteful premium spending.
Final Thoughts
San Diego BOP coverage protects your business only when you match it to your actual needs. The businesses that recover fastest after a loss took time upfront to calculate their property value accurately, identify their liability exposure honestly, and close coverage gaps before disaster strikes. Skipping this assessment costs money twice over: first through inadequate coverage that leaves you exposed, then through claim denials when you discover what your policy excludes.
Your next step is straightforward-pull together your property inventory, review your current policy declarations page, and list the specific risks your industry faces. Then request quotes from multiple carriers using consistent coverage limits and deductibles so you can compare pricing fairly. This comparison process typically takes a few hours but saves hundreds or thousands annually while ensuring your coverage actually protects what you’ve built.
At Beach Break Insurance Agency, we compare quotes from multiple top-rated carriers to deliver tailored San Diego BOP coverage that aligns with your actual needs and budget. We help you avoid both underinsurance that leaves you exposed and overinsurance that wastes premium dollars. Contact us today to get started on coverage that protects your business without the complexity.
The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation.
Artificial intelligence may have been used to generate text and images in some blog articles.


